
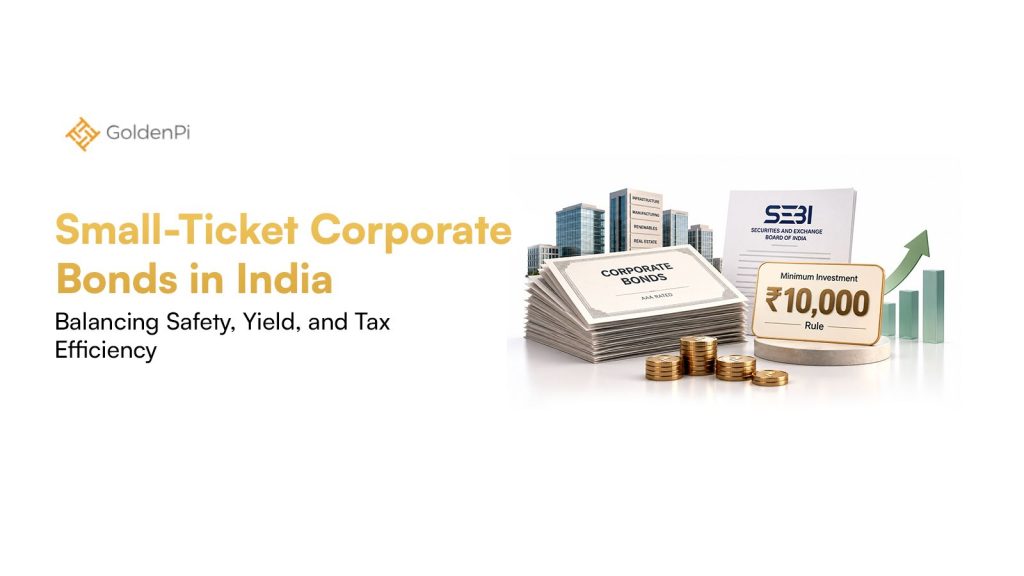
For years, only large financial institutions in India could purchase corporate bonds. A typical bond would have a face value of ₹100,000, and before 2022, bonds with face values of ₹1,000,000 were also floating in the market. That effectively locked out most individual investors, leaving them to choose between fixed deposits, mutual funds, and equities, with very little in between.
That’s not the case anymore. The Securities and Exchange Board of India (SEBI) has since reduced the minimum face value for debt securities from ₹1 lakh to ₹10,000. This, coupled with the increased number of SEBI-licensed Online Bond Platform Providers (OBPPs), has made it easier than ever for the common investor to invest in corporate debt.
But bigger crowds bring bigger scrutiny. As more first-time investors enter this space, often lured by “assured returns” language on social media, SEBI has moved to tighten how these platforms can advertise. Here’s what’s driving the shift, what the numbers say, and what to actually watch for before you click “invest.”
Start investing with just ₹10K & grow your wealth with fixed return opportunities.
Invest Now
Why Small-Ticket Bonds Suddenly Make Sense
The face-value cut didn’t happen overnight. It was a three-step climb-down:
- Pre-October 2022: Minimum face value for privately placed debt securities was ₹10 lakh, essentially institutional-only territory.
- October 2022: SEBI reduced the face value of corporate bonds to ₹1 lakh from ₹10 lakh.
- July 2024: SEBI cut the face value of debt securities further to ₹10,000 and standardized the record date to 15 days prior to any interest payment or redemption date.
With over 90% of the corporate debt issued in the private market, the expectation was that reducing the face value would result in retail investors investing in a greater variety of corporate bonds. In plain terms: most of India’s corporate debt was invisible to retail investors simply because of ticket size, not risk appetite or awareness.
The market has responded. In the AA-and-below segment, retail participation rose from around 0.8% in FY22 to 5.8% [1] in the first quarter of FY26. While this remains a relatively small share, it points to a broader expansion in retail access to corporate debt. At the same time, India’s corporate bond market recorded its highest-ever fresh annual issuance of approximately ₹9.9 trillion [2] in FY2024–25.
What’s Actually Changed for the Everyday Investor
A few structural shifts are working together here, and it’s worth separating them out:
| Change | What It Means for You |
| Minimum face value cut to ₹10,000 | You no longer need lakhs parked in one bond to diversify into corporate debt. |
| Rise of OBPPs | Bonds can be browsed, compared, and bought online, much like mutual funds. |
| Record date standardized to 15 days before interest/redemption | Predictable timelines for interest payouts across issuers |
| SEBI pushes on transparency and disclosures, plus EBP and RFQ trading systems. | Easier price discovery and more efficient trading on the secondary market |
| Falling interest rate cycle | Existing bonds with higher coupons look more attractive as fresh FD rates soften. |
For a retail investor, this means a ₹1,000 face-value NCD from a listed issuer can now sit in a portfolio the same way a debt mutual fund unit does, except you also know the exact coupon, tenure, and maturity date upfront.
The Catch: Why SEBI Is Now Policing Bond Ads
This rapid growth can attract noise, and bond platforms are no exception. SEBI has flagged increasing use of urgency-based messaging, FOMO, and promotional language on OBPP platforms that may lead to investors making hurried decisions. The regulator issued a consultation paper on August 21, 2026, proposing a revised Advertisement Code for OBPPs, inviting public comments until September 11, 2026.
Latest Bond Updates:
- ₹10,000 Corporate Bonds in India: How SEBI Made Bonds More Accessible
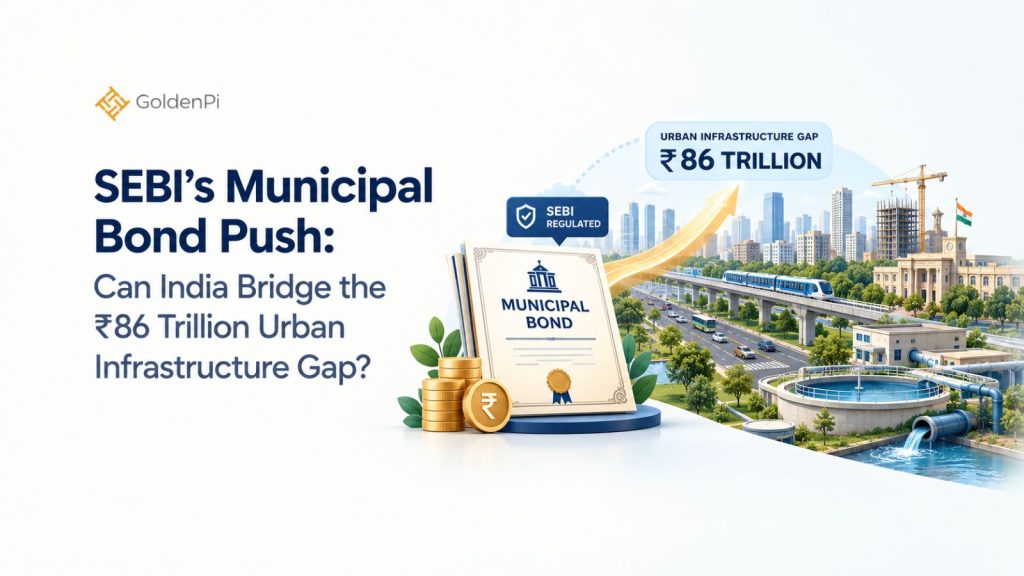
- SEBI’s Municipal Bond Push Targets India’s ₹86 Trillion Urban Infrastructure Gap
- FICP: SEBI’s New Plan to Take Corporate Bonds to Every Indian City
Some of the proposed guardrails are genuinely useful to know as an investor:
- Advertisements will need to carry a standard warning stating that fixed returns are not guaranteed and that debt securities remain exposed to market, credit, and default risks.
- Every advertisement displaying an available debt security on an OBPP platform will need to present standardized details to facilitate comparison across issues.
- Advertisements will no longer be allowed to showcase a platform’s own holdings in a debt security or ISIN, though platforms may disclose holdings separately via a prescribed holding report.
- Interestingly, SEBI will still permit terms like “fixed returns,” “predictable returns,” or “passive income,” recognising that these are accurate descriptions of how fixed-income products behave, provided they’re paired with the risk disclosures above.
This builds on an existing framework. The current OBPP advertisement code already prohibits misleading, deceptive, or exaggerated statements; requires ads to be accurate, simple, fair, and free of promotional hype; and explicitly forbids the use of celebrities, testimonials, or subjective comparisons. Existing rules also require every OBPP ad to disclose the platform’s name as registered with SEBI, its registered office address, and its SEBI registration number.
A Quick Sanity Check Before You Invest
None of this alters the fundamentals of credit risk. A ticket size of ₹10,000 does not make an NCD of a weaker issuer safer than a ₹1 lakh one did. Before you buy, it’s worth going through:
- Credit rating and rating trend: Not just what the rating is, but whether it’s been recently downgraded or is on the verge.
- Secured vs. unsecured: Whether the bond has a charge on specific assets or is a general unsecured claim.
- Coupon vs. comparable G-secs or AAA paper: A large spread over safer instruments usually signals higher risk.
- Liquidity: How actively the specific ISIN trades on the secondary market, since not all listed bonds are easy to exit before maturity.
- Platform registration: Verify the OBPP’s SEBI registration number, ideally on the SEBI or exchange website directly rather than trusting the platform’s own claim.
The Bigger Picture
India’s outstanding debt market has grown to nearly ₹275 lakh crore [3] in FY26, while the corporate bond segment stood at around ₹59.1 lakh crore. The corporate bond market has expanded at an average annual rate of 13.6% since FY12, highlighting its growing role alongside traditional bank financing. Small-ticket access and tighter advertising rules are two sides of the same coin: SEBI wants more retail money in corporate debt, but wants that money going in with eyes open, not chasing a banner on an app. For an experienced investor, that’s a reasonably good trade: a genuinely bigger opportunity set, paired with a regulator that’s actively working to keep the marketing honest.
Small-Ticket Corporate Bonds Frequently Asked Questions
Small-ticket corporate bonds are debt securities available in relatively lower denominations, allowing investors to access corporate debt without committing large amounts to a single bond.
SEBI’s 2024 framework allowed eligible debt securities to be issued with a face value of ₹10,000, subject to specified conditions. The framework was subsequently modified.
No. The ₹10,000 figure refers to the face value permitted for eligible securities under the applicable framework. It does not mean every corporate bond has a ₹10,000 minimum investment.
No. Face value is the nominal value of one bond. The actual amount an investor needs to invest can depend on the number of bonds purchased, the market price, accrued interest, and issue-specific conditions.
No. The rule reduced the denomination; it did not reduce the issuer’s credit risk, liquidity risk, interest-rate risk, or default risk.
Check the issuer, credit rating and rating rationale, secured or unsecured status, coupon, yield, maturity, liquidity, repayment structure, covenants, and applicable tax treatment.
Sources
- Financial Express — Retail investor participation in low-rated bonds jumps
- India Budget — Economic Survey 2025–26
- NSE Market Pulse — May 2026
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


