
If you’ve followed Indian credit markets, you’ve likely seen the number everywhere: securitization volumes reached approximately ₹2.5 lakh crore in FY2026 [1], representing a 5% increase from the previous year, with ICRA expecting them to reach ₹2.6-2.7 lakh crore in FY2027. Banks and NBFCs are increasingly using securitization to manage their credit-deposit ratios and liquidity, as well as to diversify their funding sources. The complexities of structured finance (SPTs, waterfalls, and tranches) can be intimidating to someone outside a structured finance desk. This article aims to break down those nuances in an easy-to-understand manner.
Start investing with just ₹10K & grow your wealth with fixed return opportunities.
Invest Now
What Is Securitization Really?
Essentially, securitization is the process of converting a bundle of loans (e.g., car loans, home loans, microfinance loans, etc.) into a security that can be sold to investors. Banks can’t hold on to thousands of individual loans and the associated EMIs for 15 years. To avoid doing so, they bundle the loans and sell the projected cash flows to investors. This frees up capital for the lender (called the originator) and gives investors access to a diversified, rated debt instrument.
Think of it like a landlord who owns 500 rental units. Instead of waiting decades to collect rent, they sell the right to that rent stream today, in exchange for a lump sum now. The buyer takes on the risk that tenants might not pay but earns a return for taking that risk.
The Special Purpose Trust (SPT): The Legal Firewall
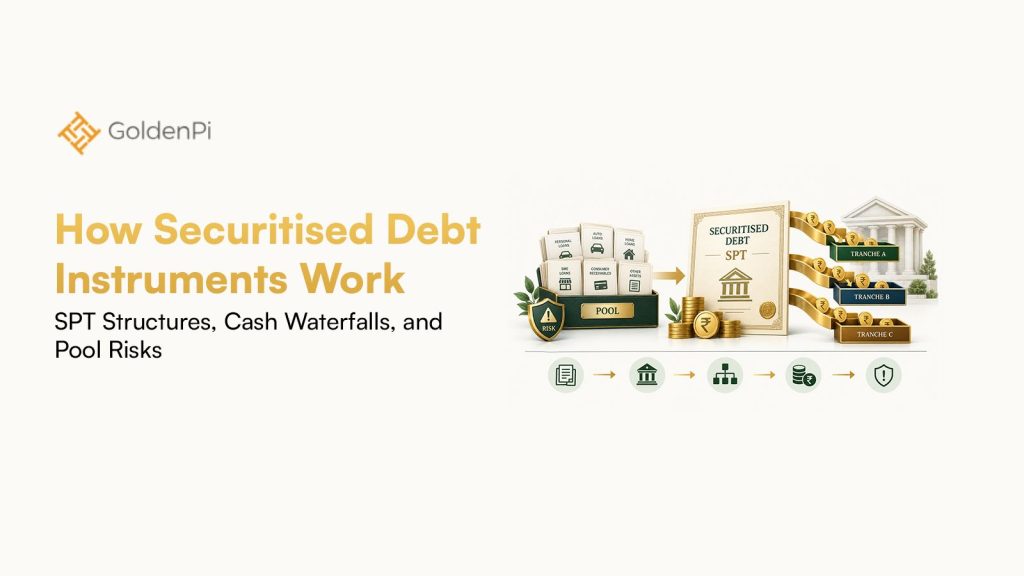
This is where the SPT comes in. The originator doesn’t sell loans directly to investors; that would tangle investor claims with the originator’s own balance sheet risk (what if the originator goes bankrupt?). Instead, the loan pool is transferred to a Special Purpose Trust: a standalone legal entity created solely to hold that pool and issue securities against it, typically as Pass-Through Certificates (PTCs).
Under RBI’s securitization framework, the SPT must be bankruptcy-remote and independent of the originator. The originator is also required to retain a Minimum Retention Requirement (MRR), so it doesn’t just sell off risky loans and walk away.
PTCs continue to be the preferred route. In FY2026, PTCs comprised about 62% of total securitisation volumes [1], a trend that has been observed since FY2024.
The Cash Waterfall: Who Gets Paid, and When
Once SPT begins collecting EMIs, cash does not get distributed randomly. It follows a strict sequence known as the cash waterfall (or payment waterfall). A simplified version looks like this:
| Priority | Payment | What it covers |
| 1 | Trustee & servicing fees | Costs of running the SPT and collecting payments |
| 2 | Senior tranche interest | Investors in the highest-rated, lowest-risk tranche |
| 3 | Senior tranche principal | Repayment of senior investors’ capital |
| 4 | Subordinate/junior tranche interest | Investors taking on more risk for higher yield |
| 5 | Subordinate tranche principal | Junior investors repaid last |
| 6 | Residual/excess spread | Returned to the originator, if anything is left |
This hierarchy is exactly why senior PTCs carry higher credit ratings (often AAA) than junior tranches; senior investors get first claim on every rupee collected. If borrowers default and collections fall short, junior investors absorb the hit first, acting as a buffer that protects senior investors. This buffer is called credit enhancement, and it’s a key reason rating upgrades in FY2025 [2] were largely driven by healthy collections building up this cushion over time as the loan pools got repaid over time.
Pool Risks: What Can Go Wrong
Even with a well-structured waterfall, the quality of the underlying pool determines everything. Key risks investors and originators watch for:
- Credit risk: Concentrated default risk within a pool is a growing concern, particularly in the case of unsecured microfinance and personal loans. Securitization of such loans was virtually stagnant during FY2025 due to rising asset quality concerns across the NBFCs [3]
- Prepayment risk: Borrowers repaying loans early leaves less money paid over the life of the loan, thus reducing the expected return for the investor
- Concentration risk: Risk associated with having huge exposure to a single originator, geography, or asset type within a pool
- Servicer risk: Dependence on the loan servicer (often the originator itself) continuing to collect and remit payments properly
- Interest rate risk: Mismatches between the pool’s fixed-rate receivables and market rate movements affecting PTC yields
Vehicle loans continue to dominate the securitization landscape in India, with a 37% share of the total volume in FY2026, followed by home/loans against property, with gold loan securitization also carving out an 11% [4] share of total market volume in H1 FY26. This asset-class concentration matters, as unfavorable movements in vehicle financing or prices of gold, for instance, could significantly impact the performance of the associated securitization pools.
Latest Bond Updates:
- All About Recurring Deposits (RDs): The Complete Investor’s Guide
- Securitised Debt Instruments Explained: SPTs, Cash Waterfalls & Pool Risks
- Where to Invest ₹1 Lakh in Fixed Income in 2026: A Practical Guide

The Bigger Picture
Securitization in India has evolved to the point that it is now critical for banks and NBFCs to manage their liquidity and capital. CRISIL reported that in FY2025, the number of issuers increased to 175 [5] from 165 the year prior, with NBFCs accounting for 92% of Q1 FY2026 [6] market volumes. RBI’s updated rules are pushing the market toward more transparency and accountability: lenders staying more accountable, better disclosure, and cleaner deal structures. That focus is only likely to get stronger as volumes keep growing.
How Securitised Debt Instruments Work Frequently Asked Questions
A securitized debt instrument (SDI) is a debt security backed by a pool of underlying receivables or debt. Instead of relying only on the financial strength of one corporate borrower, investors receive payments from the cash flows generated by the underlying pool.
SPT stands for Special Purpose Trust. In a securitisation structure, the SPT is used to hold or represent the securitised assets and facilitate the issuance of securities backed by those assets, subject to the applicable regulatory and transaction structure.
The originator is the entity that originally created or acquired the underlying receivables, such as a bank or NBFC that originated loans. The receivables are transferred into the securitization structure so that securities can be issued against their cash flows.
The pool is a collection of loans, receivables, or other eligible debt exposures whose cash flows support the securitized instrument. The composition of this pool is one of the most important factors determining the risk of the investment.
A cash waterfall is the predetermined order in which money collected from the underlying pool is distributed. Depending on the transaction, collections may first cover taxes, servicing costs, and other senior expenses before being used for interest, principal, and other investor payments.
Credit enhancement is a structural mechanism intended to absorb or reduce losses from the underlying pool. Its form can vary and may include subordination, cash collateral, excess spread, guarantees, or other permitted mechanisms.
Sources
- ICRA — “Securitisation scales new peak of Rs. 2.5 trillion in FY2026”
- ICRA — Indian Securitisation Market, June 2025 report
- Business Standard — “Securitisation volumes top Rs 68,000 crore in Q3 FY25”
- Business Standard — “Securitisation volumes rise to ₹73,000 crore in Q2 FY26”
- Business Standard — “Securitisation volumes jump 24% to hit new record of ₹2.35 trn in FY25”
- Business Standard — “Securitisation volumes up 9% at ₹49,000 crore in Q1FY26: Crisil”
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


