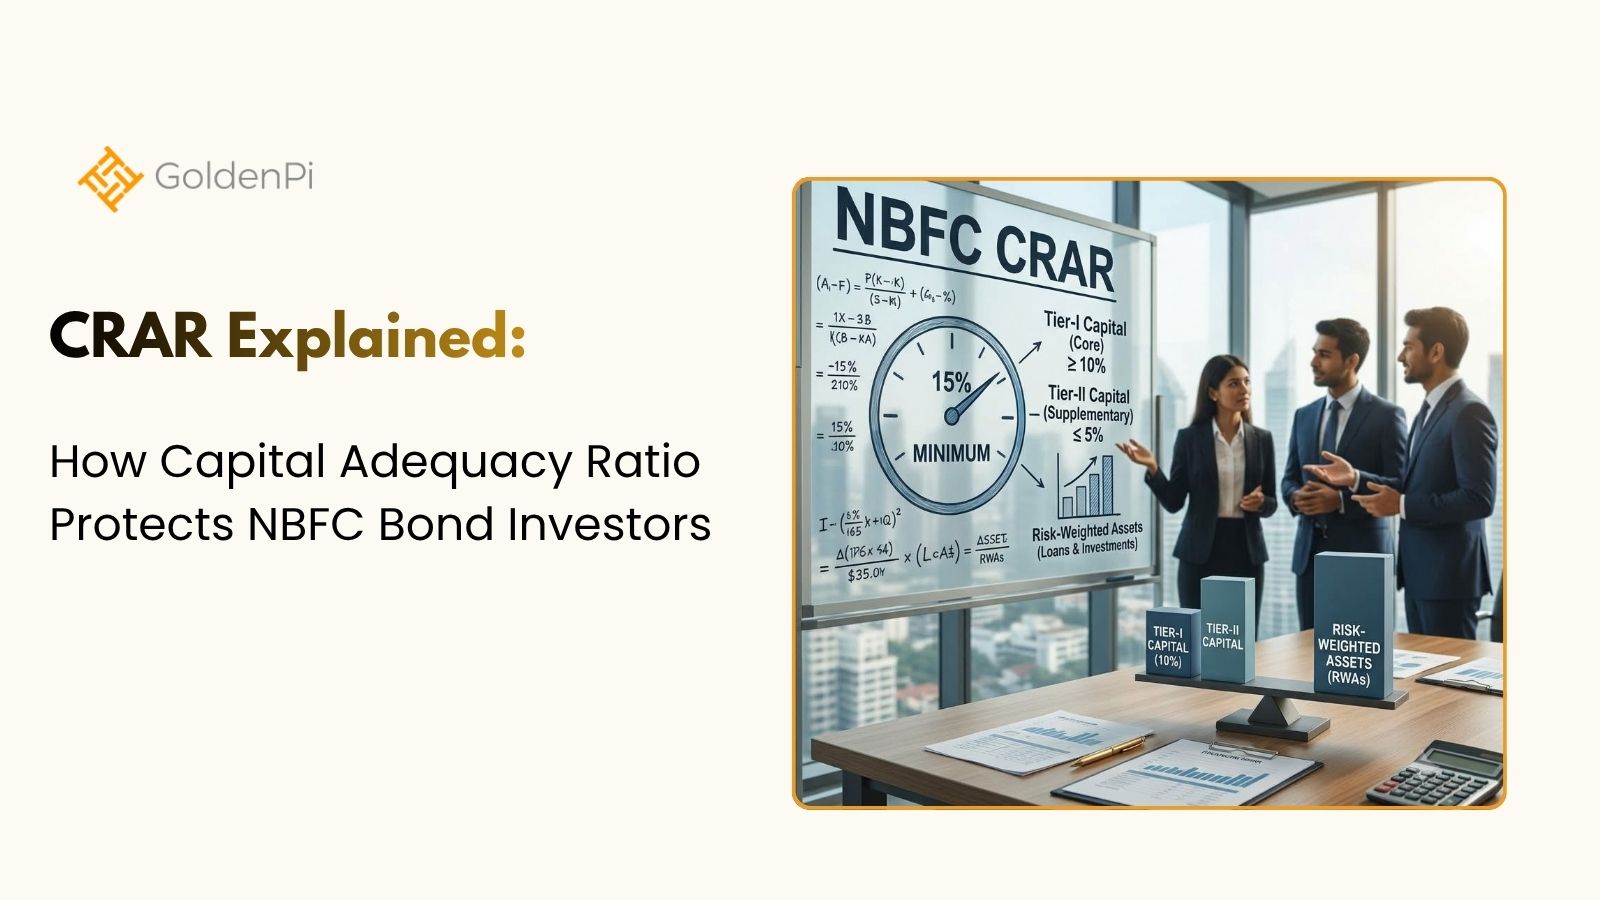
CRAR (Capital to Risk-Weighted Assets Ratio), or CAR (Capital Adequacy Ratio), measures how much loss-absorbing capital an NBFC holds against the risks on its books. For anyone buying NBFC bonds, NCDs, or fixed deposits, it works like a shock absorber: the thicker it is, the more losses the company can take before lenders are affected. This guide explains CRAR in plain language, covers the RBI’s current minimums, and shows where the ratio helps and where it can mislead.
Start investing with just ₹10K & grow your wealth with fixed return opportunities.
Invest Now
What Is CRAR, and How Is It Calculated?
The formula is simple:
CRAR = (Tier 1 capital + Tier 2 capital) ÷ Risk-weighted assets (RWA) × 100
Risk-weighted assets are the NBFC’s loans and investments, adjusted for how risky each one is. A secured, low-risk loan carries a lower weight, while an unsecured personal loan carries a higher one. So two NBFCs with equal loan books can have very different RWAs.
Example: Suppose an NBFC has ₹1,000 crore of risk-weighted assets and ₹180 crore of eligible capital, giving a CRAR of 18%. If bad loans wipe out ₹100 crore, capital drops to ₹80 crore. Holding RWA constant for simplicity, CRAR falls to 8%, well below the regulatory minimum. The cushion protected lenders, but it also shows how fast a thin buffer can disappear.
Tier 1 vs Tier 2 Capital: Which Protects You More?
Not all capital is equal. Tier 1 is the highest-quality layer, mostly equity and reserves, and it absorbs losses while the company keeps operating. Tier 2 is a weaker layer, including items such as subordinated debt, and it absorbs losses mainly when the company is winding down.
Under RBI’s capital adequacy rules [1], NBFCs in the Middle Layer and above must maintain Tier 1 capital of at least 10% of risk-weighted assets (RWAs) and a total capital-to-risk-weighted-assets ratio (CRAR) of at least 15%. Tier 2 capital cannot exceed 100% of Tier 1 capital. This limits the extent to which an NBFC can rely on supplementary capital to meet its regulatory requirement. NBFCs primarily engaged in lending against gold jewelry (where such loans account for at least 50% of financial assets) must maintain a minimum CRAR of 15% and Tier 1 capital of 12% of RWAs.
| Feature | Tier 1 capital | Tier 2 capital |
| Quality | Highest, core capital | Supplementary |
| Typical components | Equity, reserves, some perpetual instruments | Subordinated debt, certain provisions |
| Absorbs losses | While the company operates | Mainly in a wind-down |
| RBI rule | At least 10% of RWA (middle layer and above); 12% for gold-loan NBFCs | Capped at 100% of Tier 1 (general rule) |
How CRAR Protects NBFC Bond Investors
Think of an NBFC’s balance sheet as a queue for losses. Equity holders take the first hit, then Tier 1 instruments, then Tier 2 or subordinated debt. Senior bondholders rank ahead of all of these, so a higher CRAR means more layers sit between a loss and your bond.
- Loss buffer: More capital means the NBFC can absorb loan defaults without missing payments to lenders.
- Lower leverage: Capital norms stop NBFCs from lending far beyond what their capital supports.
- Rating support: Strong capital usually helps credit ratings, which can lower funding costs and improve repayment capacity.
- Regulatory attention: A weakening capital position tends to draw closer scrutiny from the RBI, often before problems become visible to investors.
RBI Capital Adequacy Norms for NBFCs (2025)
The RBI consolidated its norms under the Prudential Norms on Capital Adequacy Directions, 2025, which cover minimum Tier 1 capital, CRAR, CET1 requirements, leverage limits, and the computation of regulatory capital and risk-weighted assets. Under the scale-based framework, NBFCs are sorted into base, middle, upper and top layers, and rules get stricter as you go up. Microfinance NBFCs, for example, must keep a minimum 15% CRAR, with Tier 2 capped at 100% of Tier 1 [1].
Requirements differ by NBFC type and layer, and the RBI updates them periodically. Check the final directions and the issuer’s latest disclosures rather than assuming one number applies to every company.
Where CRAR Falls Short
A strong CRAR doesn’t make a bond safe, and it has some real blind spots. The first is that it looks backwards. CRAR reflects past profits and reported asset quality, so if bad loans haven’t been recognized yet, the ratio can look healthier than reality.
It also says little about liquidity. An NBFC can be well capitalized on paper and still struggle if it funds long-term loans with short-term borrowing. The 2018 IL&FS episode showed how quickly funding stress can reach bondholders.
Risk weights add another layer of uncertainty, since they are regulatory rules rather than real-world outcomes. A loan can look low-risk on the RWA scale and still turn out badly. Finally, the mix of capital matters as much as the headline number: a 20% CRAR built mostly on Tier 2 capital is weaker than a 20% CRAR built on Tier 1.
L(earn) More
- CRAR Explained: How Capital Adequacy Ratio Protects NBFC Bond Investors
- Muthoot Fincorp NCD IPO October 2026: Minimum Investment, Rates & Details
- Bond Buybacks Explained: Should You Tender or Hold Your Corporate Debt?

NBFC Bond Checklist: What to Check Besides CRAR
- Check CRAR and Tier 1 together. Look for a clear cushion above the RBI minimums, not a number sitting right at the floor.
- Look at asset quality. Gross and net NPAs, Stage 3 assets and restructured loans show how clean the loan book really is.
- Review the asset-liability profile. Mismatches between short-term borrowings and long-term loans signal refinancing risk.
- Read the credit rating rationale. Rating agencies often explain capital trends and management quality in detail.
- Know where your bond ranks. Senior secured NCDs sit higher than subordinated debt or perpetual bonds, which carry more risk and often higher yields for a reason.
Is a High CRAR Enough? What NBFC Bond Investors Should Remember
CRAR is a useful first filter for NBFC bond investors in India, and a strong ratio built mainly on Tier 1 capital is a good sign. But treat it as one input, not a verdict. Pair it with asset quality, liquidity, ratings and your bond’s seniority before committing money. If you’re unsure, a SEBI-registered investment adviser can help you compare issuers.
CRAR in an NBFC? FAQs
CRAR stands for Capital to Risk-Weighted Assets Ratio. It measures an NBFC’s eligible regulatory capital relative to its risk-weighted assets. A higher CRAR generally indicates a larger capital buffer to absorb losses.
Not necessarily. A higher CRAR can indicate a stronger capital buffer, but it does not reveal the full quality of the NBFC’s loan book, liquidity position, funding profile or asset-liability mismatches. Investors should assess these factors alongside CRAR.
Risk-weighted assets are assets and certain off-balance-sheet exposures adjusted using regulatory risk weights. Exposures considered riskier generally attract higher weights. This means two NBFCs with similar total assets can have different risk-weighted assets and CRARs.
Tier 1 capital is the core layer of regulatory capital intended to absorb losses while the NBFC continues operating. Depending on the applicable rules, it includes eligible owned funds and certain qualifying capital instruments. It is generally considered a more important indicator of capital quality than relying on total capital alone.
Tier 2 capital is supplementary regulatory capital that can include eligible subordinated debt, certain provisions and other permitted instruments. It adds to an NBFC’s capital buffer, subject to regulatory limits and eligibility conditions.
Yes. CRAR is not a measure of cash available to pay bondholders on a particular date. An NBFC could have adequate regulatory capital but face a liquidity shortage, large near-term repayments, deteriorating collections or difficulty refinancing its liabilities.
A breach can trigger regulatory scrutiny and corrective action, depending on the circumstances and applicable RBI requirements. It may also affect the NBFC’s ability to grow its loan book or raise funding. For bond investors, a breach is a warning sign that warrants closer examination of the issuer’s disclosures and financial condition.
Sources
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


