
If you’re a woman building a fixed-income portfolio in India — whether it’s for retirement, your daughter’s education, or simply to balance out riskier equity bets — you’ve probably run into this exact dilemma: Post Office schemes or corporate bonds? Both seem like safe bets, but they work differently. With Post Office schemes, you get government backing, which means your principal is virtually safe.
On the other hand, corporate bonds are issued by companies, and they offer higher yields, but that extra return comes with credit risk, since you’re essentially betting on the company’s ability to repay you, not the government’s. This guide breaks it all down in simple terms, so you can decide what works best for your goals, risk tolerance, and tax situation.
Start investing with just ₹10K & grow your wealth with fixed return opportunities.
Invest Now
Post Office Schemes: The Safety-First Option
Post Office savings schemes, run under the National Small Savings Scheme (NSSS) umbrella, are among the safest instruments in India because they carry a sovereign guarantee. The Ministry of Finance revises these rates every quarter, and for the current quarter (July–September 2026), here’s where things stand:
| Scheme | Interest Rate (p.a.) | Tenure | Tax Deduction (Old Regime, Sec. 123) |
| Post Office Savings Account | 4.00% | Ongoing | No |
| Recurring Deposit (RD) | 6.70% | 5 years | No |
| Time Deposit (1 yr) | 6.90% | 1 year | No |
| Time Deposit (2 yr) | 7.00% | 2 years | No |
| Time Deposit (3 yr) | 7.10% | 3 years | No |
| Time Deposit (5 yr) | 7.50% | 5 years | Yes |
| Monthly Income Scheme (MIS) | 7.40% | 5 years | No |
| Public Provident Fund (PPF) | 7.10% | 15 years | Yes (completely tax-free) |
| National Savings Certificate (NSC) | 7.70% | 5 years | Yes |
| Senior Citizen Savings Scheme (SCSS) | 8.20% | 5 years | Yes |
| Sukanya Samriddhi Yojana (SSY) | 8.20% | 21 years after opening | Yes (completely tax-free) |
Source: India Post
Note:
- Deduction under Section 123 (formerly Section 80C), capped at ₹1.5 lakh, is available only if you opt for the old tax regime; it does not apply under the new (default) tax regime.
- Rates shown are for the Small Savings Schemes quarter of July–September 2026, as notified by the Ministry of Finance. These are reviewed every quarter, so it’s worth checking for updates before you invest.
For instance, if you’re saving for a daughter under 10, the Sukanya Samriddhi Yojana at 8.20% (tax-free at every stage) is hard to beat on a risk-adjusted basis. That’s the kind of “boring but reliable” return Post Office schemes are known for.
Corporate Bonds: Higher Yield, Different Risk
Corporate bonds are debt instruments issued by companies (PSUs, NBFCs, or private corporates) to raise money. In exchange for lending them your money, you earn periodic interest (coupon) and get your principal back at maturity. Except, unlike Post Office schemes, there’s no sovereign guarantee backing these up, so if the company hits a rough patch, your returns, and even your initial investment, could be at risk. That’s where credit ratings matter: a lower rating usually means a higher yield to make up for the extra risk you’re taking on.
As of September 2026, AAA-rated PSU bonds (think PFC, REC, IRFC, NHAI, etc.) have generally been trading around the 7.0%–7.7% range, with yields varying by issuer, maturity, and market price. AAA-rated bonds from private NBFCs (like Bajaj Finance or Tata Capital), which don’t have the same government ownership or support framework as PSU issuers, have generally been trading somewhat higher, with yields in some cases around 7.5%–8.3%. And then there are AA+ rated bonds, which can trade at still higher yields, with some securities in the 7.8%–8.6% range. These are indicative ranges rather than fixed market-wide bands, since bond yields change with maturity, liquidity, credit spreads, and secondary-market prices.
Let’s consider a simple example: Say you’re weighing a 5-year AAA-rated PSU bond that yields around 7.3% against a 5-year Post Office Time Deposit offering 7.5%. Here, the supposedly “safer” government-backed option actually pays more, which serves as a reminder that corporate bond yields are subject to market fluctuations and don’t always trump government-backed alternatives. So, it’s crucial to check current numbers before assuming corporate bonds always “win” in terms of return.
Latest Bond Updates:
- India’s 10-Year Bond Yield Near Two-Year High as Crude Tops $106, US Yields Surge
- Post Office Schemes vs Corporate Bonds: A Guide for Women Investors in 2026
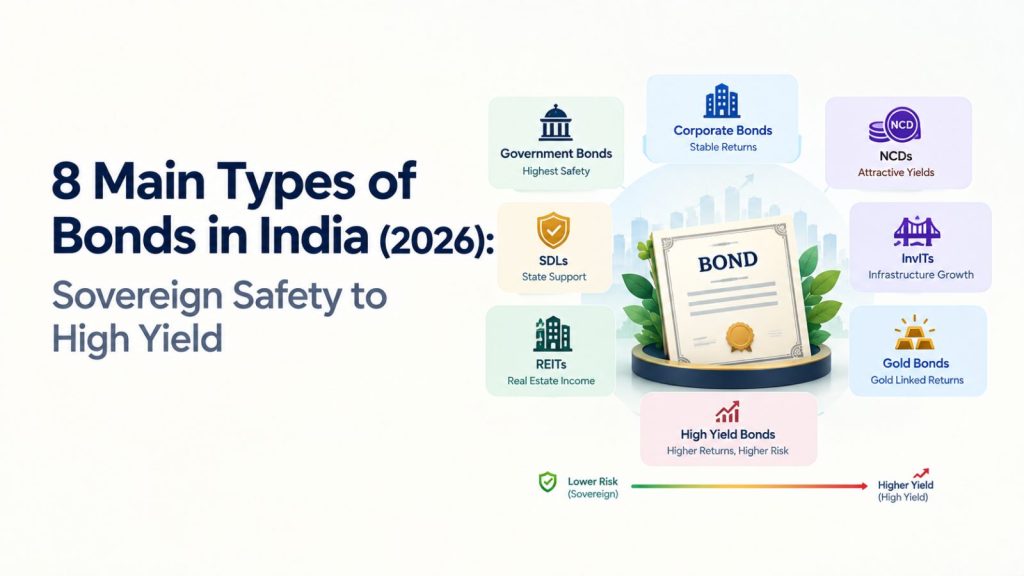
- 8 Main Types of Bonds in India (2026): Sovereign Safety to High Yield
Post Office Schemes vs. Corporate Bonds: Key Differences
- Safety: Post Office schemes carry a sovereign guarantee; corporate bonds depend on the issuer’s creditworthiness and rating.
- Liquidity: Most Post Office schemes have lock-ins, and if you need to withdraw early, your options are limited; listed corporate bonds can be sold on stock exchanges before they mature, but liquidity varies greatly from one bond to another.
- Returns: Fixed and government-notified for Post Office schemes; corporate bond yields, however, can fluctuate based on the issuer, rating, and tenure and can be significantly higher for lower-rated bonds.
- Taxation: Several post office schemes offer Section 123 (formerly Section 80C) benefits, but only if you’ve opted for the old tax regime; corporate bond interest is fully taxable according to your income slab, with no special exemptions in most cases.
- Minimum investment: Post Office schemes often start as low as ₹250–₹1,000; corporate bonds typically require higher ticket sizes, though online bond platforms have brought this down for many listed bonds.
- Who regulates it: Post Office schemes fall under the Ministry of Finance; corporate bonds and the platforms that sell them are regulated by SEBI.
Which One Should Women Investors Choose?
There’s no universal answer. It depends on your goals, time horizon, and how much risk you’re comfortable holding.
- If you want capital protection above everything else (say, for an emergency fund or a near-term goal), Post Office schemes like SCSS (if you qualify) or a Time Deposit make more sense.
- If you’re investing for long-term wealth with tax efficiency, PPF or SSY (for a daughter’s future) are strong, low-maintenance options.
- If you already have a solid safety net and want to diversify into slightly higher-yielding instruments, high-rated (AAA/AA) corporate bonds can be a reasonable addition, in moderation, and after checking the issuer’s rating, tenure, and liquidity.
- A mixed approach: anchoring your portfolio in Post Office schemes while allocating a smaller slice to well-rated corporate bonds is how many financial planners suggest balancing safety with a bit of extra yield.
Before You Invest: A Closing Word on Corporate Bonds
If there’s one place to slow down in this comparison, it’s here. Choosing whether corporate bonds fit your portfolio is one decision; choosing which bond and how much to put into it is a separate one, and it deserves its own discipline.
Start with the paperwork: read the actual offer document or information memorandum rather than relying on a platform’s summary. It will spell out the coupon structure, call/put options, if any, and what happens in case of delayed payments. Check whether the bond is listed on an exchange, since that affects how easily you can track its price and exit if your plans change. And resist the urge to put a large chunk of your allocation into a single issuer, however attractive the coupon looks; spreading it across two or three well-rated names limits the damage if one of them stumbles.
None of this eliminates risk; nothing in corporate debt does, but it’s what turns a headline yield into an informed decision rather than a hopeful one.
Post Office Scheme Frequently Asked Questions
Women can use eligible Post Office small-savings products such as Post Office Time Deposits, National Savings Certificates (NSC), Monthly Income Account, Public Provident Fund (PPF), and Sukanya Samriddhi Account for an eligible girl child and other applicable schemes. Eligibility and rules vary by product.
They can, but a higher yield generally comes with additional risk. Corporate bond returns depend on the issuer, rating, maturity, market price, and other terms, so the headline yield should not be compared with a Post Office rate in isolation.
At minimum, check credit/default risk, interest-rate risk, liquidity risk, maturity, rating, issuer financials, and the bond’s security or seniority. SEBI specifically identifies default, interest rate, and liquidity risks among the key risks of bonds.
Both can provide income, but their structures differ. The Post Office Monthly Income Account is specifically designed around periodic interest payments, while corporate bonds have coupon schedules specified in their individual terms. Compare payment frequency, rate, tenure, and risks before choosing.
Neither should be treated as universally liquid. Post Office products have scheme-specific premature withdrawal rules, while corporate bonds depend on secondary-market demand. A listed corporate bond is not automatically easy to sell.
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


