
Issuer Name
Credit rating
Calculate returns
Issue details
Allocation by investor category
Muthoot Fincorp NCD – Key Issue Details
Senior Secured Redeemable Non-Convertible Debentures
| Issuer | MUTHOOT FINCORP LIMITED |
| Type of instrument | Senior Secured Redeemable Non-Convertible Debentures |
| Listing | BSE |
| Base Issue Size | Rs. 200 Cr |
| Option to retain Oversubscription | Rs. 300 Cr |
| Issue Size | Rs. 500 Cr |
| Issue Price | Rs. 1000/- Per NCD |
| Minimum Investment | Rs. 10,000/- (10 NCD) and in multiples of Rs. 1,000/- (1 NCD) thereafter. |
| Credit Rating | |
| Trustee | Vardhman Trusteeship Private Limited |
| Registrar | Integrated Registry Management Services Private Limited |
| Issue Opening Date | Friday, October 23, 2026 |
| Issue Closing Date | Thursday, November 05, 2026 |
| Mode of Application | ASBA only |
| Mode of Allotment | Dematerialized only |
| Allotment | First Come First Serve Basis |
| Depositories | NSDL and CDSL |
Muthoot Fincorp Limited NCD: Purpose of the Issue
Proceeds from the IPO will be utilized for—
- Primarily for the onward lending, financing, and repayment/prepayment of interest and principal of existing borrowings of the Company
- General corporate purpose
Muthoot Fincorp NCD Interest Rates and Effective Yields
The NCDs are being issued twelve different series to cater to different investor needs, ranging from short-term liquidity to long-term wealth compounding
NCD Coupon Rates & Effective Yield Details
Comprehensive series breakdown across payment frequencies, tenors, coupon rates, and effective yields.
| Series | Frequency of Interest Payment |
Nature | Tenor | Coupon (% per Annum) |
Effective Yield (% per Annum) |
|---|---|---|---|---|---|
| 1 | Monthly | Secured | 24 Months | 8.56% | 8.89% |
| 2 | Monthly | Secured | 36 Months | 8.75% | 9.10% |
| 3 | Monthly | Secured | 60 Months | 8.84% | 9.20% |
| 4 | Monthly | Secured | 72 Months | 8.88% | 9.24% |
| 5 | Annual | Secured | 24 Months | 8.90% | 8.89% |
| 6 | Annual | Secured | 36 Months | 9.10% | 9.09% |
| 7 | Annual | Secured | 60 Months | 9.20% | 9.19% |
| 8 | Annual | Secured | 72 Months | 9.25% | 9.24% |
| 9 | Cumulative | Secured | 24 Months | NA | 8.90% |
| 10 | Cumulative | Secured | 36 Months | NA | 9.10% |
| 11 | Cumulative | Secured | 60 Months | NA | 9.20% |
| 12 | Cumulative | Secured | 72 Months | NA | 9.25% |
Best yield: 9.25% (Series 12, 72 Months cumulative payout).
Understanding the Allocation Ratio:
The allocation ratio is prepared based on norms laid down by SEBI. Before announcing the allocation ratio, the same has to be approved by SEBI. Once the IPO subscription closes, applications will be divided into different categories.
Recent NCD IPOs:
- Muthoot Fincorp NCD IPO October 2026: Minimum Investment, Rates & Details
- SMC Global, Securities NCD Issue 2026: 10% Yield, Rating, Details, and How to Invest
- Edelweiss Financial Services Limited NCD IPO
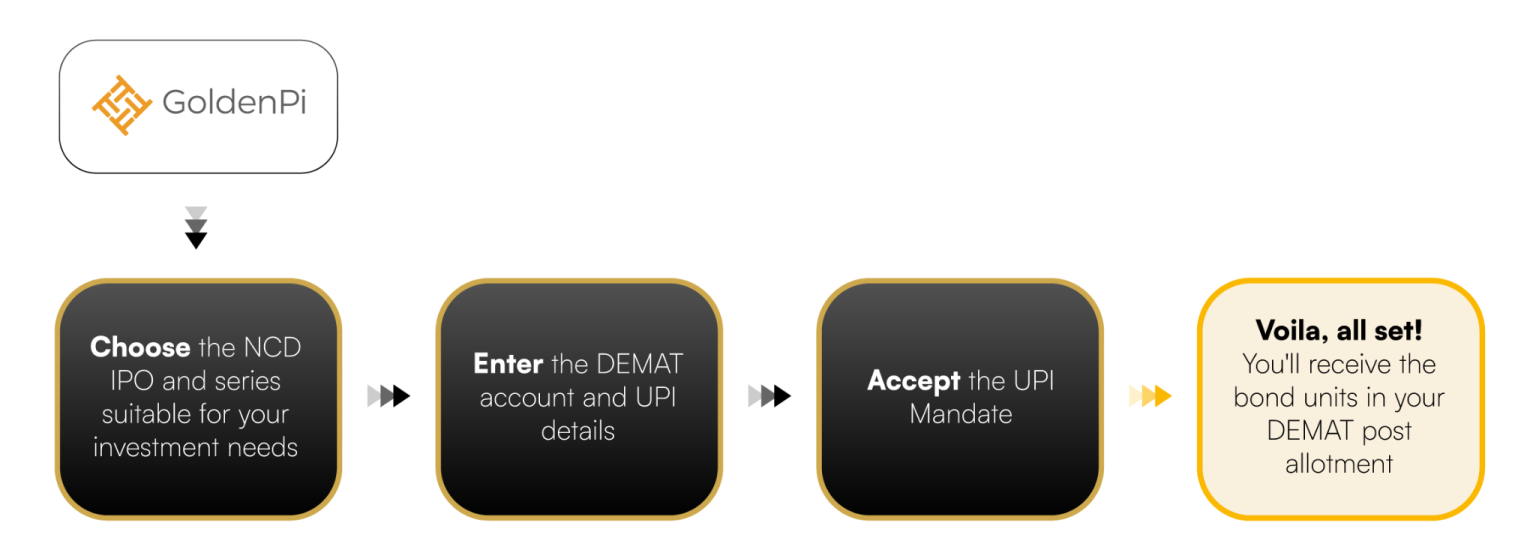
How to Invest in Muthoot Fincorp NCD IPO via GoldenPi
Investing in Bond IPOs is now seamless. Follow these easy steps:
- Log in to GoldenPi.
- Look for the Search option and type Muthoot Fincorp
- Select Muthoot Fincorp NCD IPO
- Choose your series and apply via UPI.
Financial Overview of Muthoot Fincorp Limited:
A deep dive into the company’s balance sheet reveals a consistent growth trajectory in revenue and net worth.
Snapshot stating the Revenue, Expenses, PAT and Net-worth (In crores):
Recent Muthoot NCD IPOs:
- Muthoot Fincorp NCD IPO October 2026: Minimum Investment, Rates & Details
- Muthoot Fincorp Limited NCD IPO September 2026: Should You Invest? Interest Rates, Review, Dates & Credit Rating
- Muthoot Fincorp NCD IPO: Issue Details, Returns, and Risks
Cash Flow Analysis (In crore):
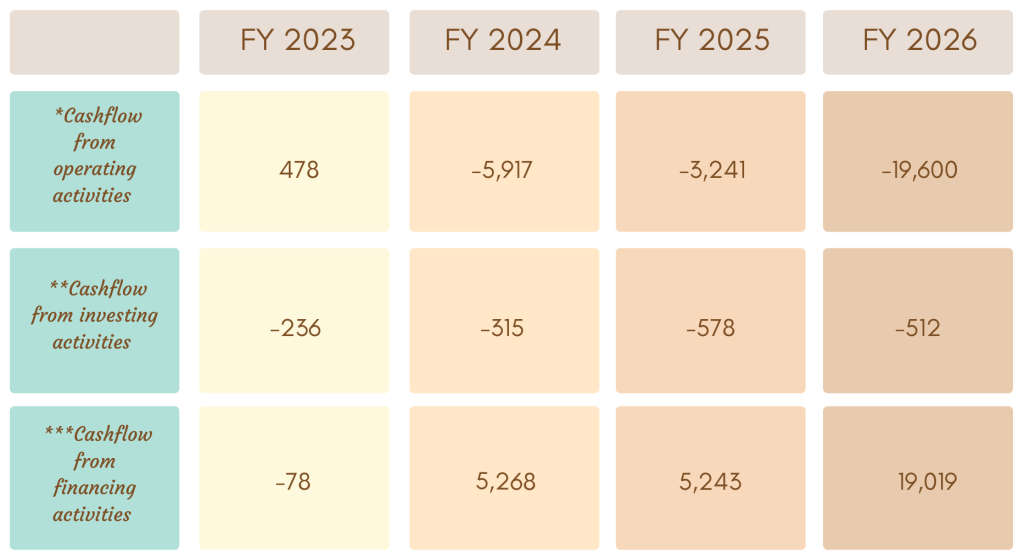
Cash flow refers to the movement of cash in and out of the business at a specific point in time. It represents the net balance of the cash movement.
- Cash flow from operating activities reflects the amount a company generates through its product of services.
- Cash flow from investing activities reflects cash generated and spent relating to investing activities, like purchase of assets, sales of securities etc.
- Cash flow from financing activities gives an insight into the financial stability of a company to its investors. It reflects the net flows of cash that are used to fund the company.
Ratio Analysis:
| Ratio | What Does It Mean | Benchmark | Trend | Analysis | Assessment |
|---|---|---|---|---|---|
| Net NPA | Net NPA is the subtraction of provisions related to unpaid debt from GNPA. This gives the exact value of bad loans. It is a better indicator of NBFCs’ health. | Maximum 6% |
Net NPA
|
The decrease in this ratio between FY25 and FY26 represents a favorable trend. Furthermore, since the ratio continues to stay within the limits established by the RBI, it indicates the NBFC maintains a healthy financial position. | GOOD |
| Capital Adequacy Ratio | Capital Adequacy Ratio (CAR) is a measure of the degree to which the company’s capital is available to absorb unexpected loss. | Minimum 15% |
Capital Adequacy Ratio (CAR)
|
The ratio has been decreasing over the years but matches the benchmark criteria of RBI. This represents that the NBFC might be able to meet its unexpected losses through its available capital. | GOOD |
| Debt to Equity ratio | Debt-to-Equity ratio reflects the risk appetite of the company. This is a very important leverage ratio. It reflects the ability of a company to make payments associated with overall debt. | Not more than 7:1 |
Debt-Equity Ratio
|
The ratio has been increasing over the years. This could be due to more funding needs as they are expanding their branches. The ratio falls under the benchmark criteria, representing that the NBFC might be able to meet its debt obligations with equity when earnings are low. | GOOD |
Should You Invest? Pros & Cons of Muthoot Fincorp NCD
Click on any point to view detailed analysis
Robust Credit Profile
Positive Rating Momentum
Asset Protection
Security Cover
Competitive Yields
Flexible Tenors & Payouts
BSE Listed
Gold Loan Volatility Exposure
Interest Rate Risk
Structural Subordination & Dilution
About Muthoot Fincorp Limited:
Muthoot Fincorp Ltd. (MFL), incorporated in 1997 and registered with the RBI, is a Kerala-based, non-deposit-taking NBFC. It primarily offers small-ticket “gold loans” against household gold jewelry, a segment where it has over two decades of experience.
Muthoot Fincorp Ltd., the flagship entity of the diversified Muthoot Pappachan Group (also known as Muthoot Blue Group), also provides secured and unsecured MSME lending. Beyond lending, the company offers mutual fund and insurance distribution and foreign exchange/money transfer services and operates as a Category II Depository Participant (DP) of CDSL.
Its three subsidiaries are Muthoot Housing Finance (affordable housing loans), Muthoot Microfin (micro credit to women entrepreneurs), and Muthoot Pappachan Technologies (IT services).
As of June 30, 2026, its AUM (Asset Under Management) stood at ₹73,445 Cr on a consolidated basis and ₹56,185 Cr, on a standalone basis.
MFL has a strong pan-India presence, operating approximately 3,845 branches (31st June, 2026) and 326 processing centres across 25 states/UTs, with key presence in Kerala, Tamil Nadu, Karnataka, Andhra Pradesh, Telangana, and Maharashtra.
To support its next phase of growth and strengthen its capital base, the company’s Board of Directors has approved an Initial Public Offering (IPO) aimed at raising up to ₹4,000 crore
Company Profile: Strengths & Weaknesses
Click on any section to view full operational analysis
Experienced Management & Strong Promoter Commitment
Predominantly Secured Retail Portfolio
Adequate Capitalisation
AUM Growth
Improving Profitability Profile
Healthy Asset Quality
Diversified Funding Profile
Strong Liquidity
Regional Concentration Risk
High Reliance on Gold Loan Segment
Invest Now: Invest in Bond IPO online in just 5 minutes
Source: Tranche I Prospectus October 19, 2026 and Annual Report FY26 – Check Now
Disclaimer –The information is published as on date 23/10/2026 based on information available on Tranche I Prospectus October 19, 2026. The information may be subject to change in case of change in terms of prospectus or any other reason as the case may be. Contents which are exclusively for educational information/knowledge sharing on capital market concepts and have no influence on the investment/sale decisions of any investors.


