
The subscription window opens from September 21 to October 5, 2026, with allotments processed on a First-Come, First-Served (FCFS) basis on the BSE.
Edelweiss Financial Services NCD: Issue Overview
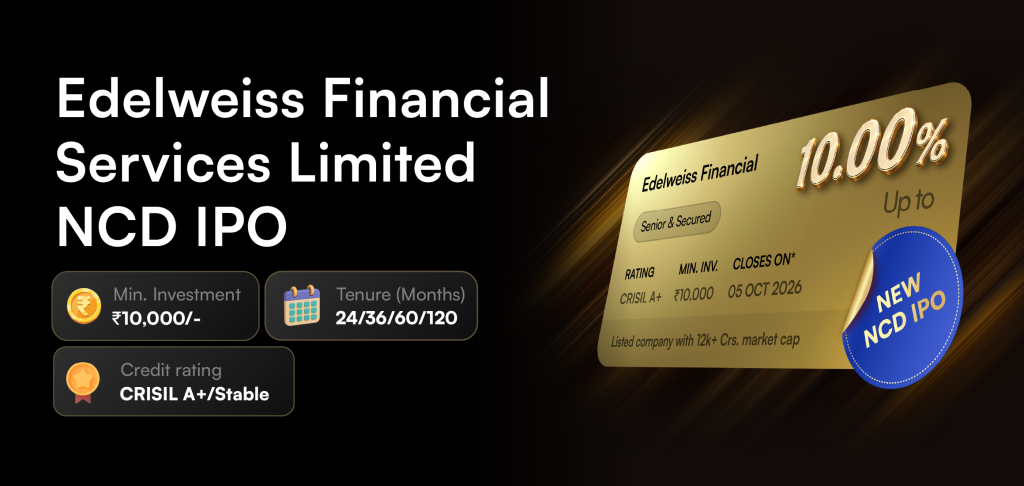
- Credit Rating: A+/Stable (CRISIL)
- Yield Range: 8.64% to 10.00% p.a.
- Tenures: 24, 36, 60, and 120 months.
- Nature: Secured and Redeemable.
- High Yield | CRISIL A+/Stable Rated | Minimum Investment: 10k Only
Edelweiss Financial Services NCD – Key Issue Details
Senior Secured Redeemable Non-Convertible Debentures
| Issuer | Edelweiss Financial Services Limited |
| Type of Instrument | Senior Secured Redeemable Non-Convertible Debentures |
| Listing | BSE |
| Base Issue Size | Rs. 150 Cr |
| Option to Retain Oversubscription | Rs. 150 Cr |
| Issue Size | Rs. 300 Cr |
| Issue Price | 1000/- Per NCD |
| Minimum Investment | Rs. 10,000/- (10 NCD) and in multiples of 1,000/- (1 NCD) thereafter. |
| Credit Rating | |
| Trustee | Beacon Trusteeship Limited |
| Registrar | KFin Technologies Limited |
| Issue Opening Date | Monday, September 21, 2026 |
| Issue Closing Date | Monday, October 5, 2026 |
| Mode of Application | ASBA only |
| Mode of Allotment | Dematerialized only |
| Allotment | First Come First Serve Basis |
| Depositories | NSDL and CDSL |
Edelweiss Financial Services NCD Coupon rates and effective yield
The NCDs are being issued in ten different series to cater to different investor needs, ranging from short-term liquidity to long-term wealth compounding
| Series | Frequency of Interest Payment |
Tenor | Coupon (% per Annum) |
Effective Yield (% per Annum) |
|---|---|---|---|---|
| 1 | Annual | 24 Months | 8.65% | 8.64% |
| 2 | NA | 24 Months | NA | 8.65% |
| 3 | Monthly | 36 Months | 8.80% | 9.15% |
| 4 | Annual | 36 Months | 9.15% | 9.14% |
| 5 | NA | 36 Months | NA | 9.15% |
| 6 | Monthly | 60 Months | 9.21% | 9.60% |
| 7 | Annual | 60 Months | 9.60% | 9.59% |
| 8 | NA | 60 Months | NA | 9.60% |
| 9 | Monthly | 120 Months | 9.58% | 10.00% |
| 10 | Annual | 120 Months | 10.00% | 9.99% |
Understanding the Allocation Ratio
The allocation ratio is prepared based on norms laid down by SEBI. Before announcing the allocation ratio, the same has to be approved by SEBI. Once the IPO subscription closes, applications will be divided into different categories.
Investor Category Allocation
How to Invest in Edelweiss Financial Services NCD IPO via GoldenPi
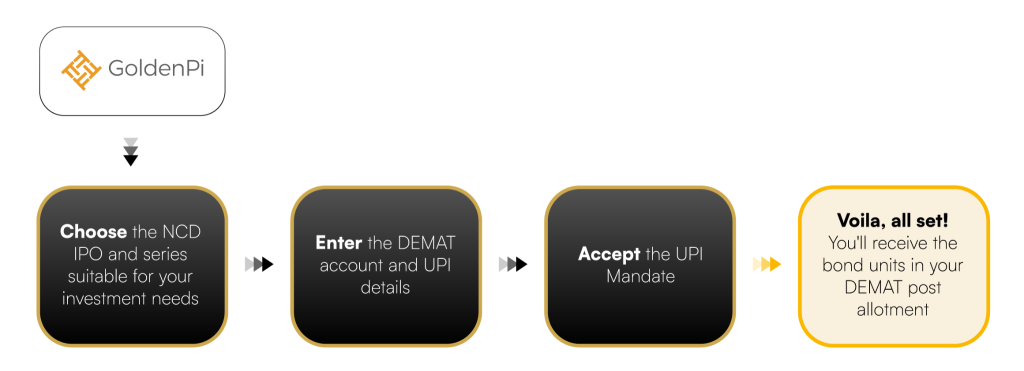
Investing in Bond IPOs is now seamless. Follow these easy steps:
- Log in to GoldenPi.
- Look for the Search option and type Edelweiss Financial Services
- Select Edelweiss Financial Services NCD IPO
- Choose your series and apply via UPI.
Recent NCD IPOs:
- SMC Global, Securities NCD Issue 2026: 10% Yield, Rating, Details, and How to Invest
- Edelweiss Financial Services Limited NCD IPO
- Muthoot Fincorp Limited NCD IPO September 2026: Should You Invest? Interest Rates, Review, Dates & Credit Rating
Financial Overview of Edelweiss Financial Services
A deep dive into the company’s balance sheet reveals a consistent growth trajectory in revenue and net worth.
Snapshot stating Total Income, Expenses, Net Worth, and PAT (In crores)
Snapshot stating Total Income, Expenses, Net Worth and PAT (In crores)
Cash flow for the last few years (In crores)
Cash flow refers to the movement of cash in and out of the business at a specific point in time. It represents the net balance of the cash movement.
Cash flow from financing activities gives an insight into the financial stability of a company to its investors. It reflects the net flows of cash that are used to fund the company.
Cash flow from operating activities reflects the amount a company generates through its product of services.
Cash flow from investing activities reflects cash generated and spent relating to investing activities, like purchase of assets, sales of securities, etc.
| FY 2023 | FY 2024 | FY 2025 | FY 2026 | |
|---|---|---|---|---|
| *Cashflow from operating activities |
1720 | 2894 | 3384 | 897 |
| **Cashflow from investing activities |
745 | -482 | 3793 | -963 |
| ***Cashflow from financing activities |
-1708 | -2785 | -4828 | -1936 |
Issue analysis
Pros & Cons
Pros
- Strong Credit Rating: Rated Crisil A+/Stable, indicating a high degree of safety and low credit risk.
- Secured NCDs: Senior secured NCDs backed by clear charge on assets (loan and advances, receivables, investments, stock in trade, current & other assets, immovable property / fixed assets).
- Security Cover: The security cover required must be a minimum of 100% of the total of the outstanding principal balance of the NCDs.
- Competitive yields: Up to 10.00% vs bank FDs (6.5 – 8%) and AAA corporate bonds.
- Wide tenor and payout frequencies: 24/36/60/120 Months and Monthly/ Annual interest payment payouts providing flexibility to investors.
- BSE listed: Provides secondary market liquidity option.
Cons
- Interest Rate Risk: More pronounced in longer tenors (60 and 120 months).
- Pari Passu Charge (Shared Collateral): The pledged assets are shared with other creditors. In case of default, NCD investors do not have exclusive rights over the security and must share recoveries with other lenders.
Must Check: To get better returns than Bank FDs, invest in NCD-IPOs online.
About Edelweiss Financial Services Limited
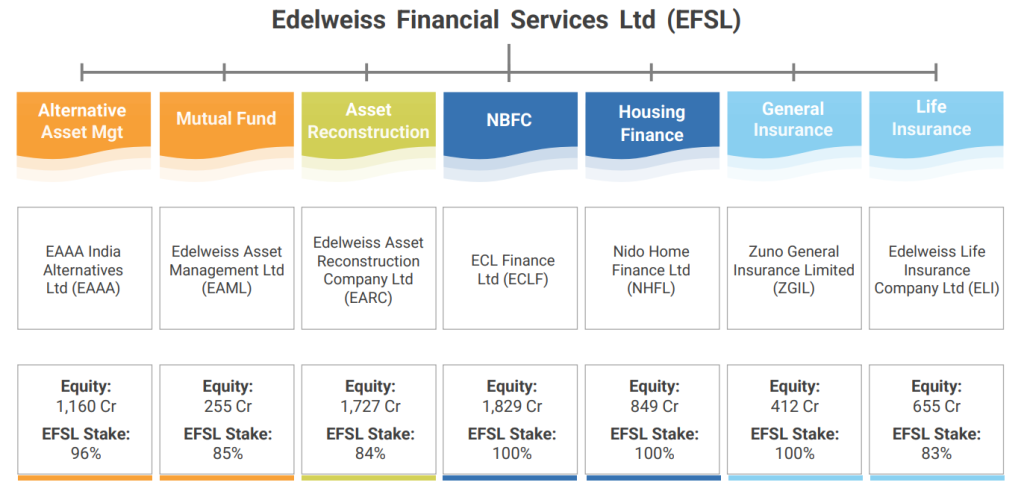
Edelweiss Financial Services Limited is one of India’s leading financial services conglomerates, offering a robust platform to a diversified client base (1.42+ crore) across domestic (307) and global (3) geographies. The company has mainly four business verticals, namely Retail Credit (Mortgage & MSME loans), Asset Management (Mutual Funds & Alternatives), Asset Reconstruction and Insurance services (General & Life). Apart from that, the company has also been providing Merchant Banking services since 1995. Edelweiss Financial Services Limited is listed on the stock exchange, having a market capitalization of more than ₹12,700 Crores as of Sept 2026.
Strengths:
- Strong Brand & Nationwide Network: Edelweiss has a strong presence across India with 307 offices, backed by a reputation for execution and innovation.
- Experienced management team: leadership is stable, characterized by extensive experience. Chairman & MD, Rashesh Chandrakant Shah (35+ yrs), and Vice Chairman & Director, Venkatchalam A. Ramaswamy (30+ Yrs) in the BFSI sector
- Strong Institutional Backing: Promoters hold 32.3%, FIIs hold 19.2%, and DIIs & non-institutions hold 47.9%. Marquee investors include LIC (2.6%), Vanguard group (2.4%), Blackrock (1.3%), and Barclays (0.9%).
- Strong funding partners and Network: JP Morgan, HSBC, Bill & Melinda gates foundation, Bank of Baroda, TATA Trusts, HCL, WIPRO, ICICI Prudential, and Zerodha
- Diversified business model : Presence in Asset reconstruction (ARC), asset management (Alternate asset & Mutual Funds), Credit (MSME & Mortgages ), Insurance (Life & General) – mitigates reliance on lending alone.
- Adequately capitalised: Edelweiss group NBFCs – ECL Finance (27%), Nido Home Finance (30%), and Edelweiss ARC (36%) – are well-capitalized, with CRAR significantly above the RBI’s 15% minimum.
- Stable asset quality: The Net-NPA for the three credit entities (ECL Finance, Nido Home Finance, Edelweiss Retail Finance Limited) remained controlled: 1.70% (FY25), 1.29% (FY24), and 1.36% (FY23).
- Significantly reducing debt over medium term: Net debt reduced materially from ₹18,550 crore (Mar ’22) to ₹11,170 crore (Mar ’26), reflecting balance sheet repair through recoveries, stake sales and fee-led earnings.
- Asset management franchise has scaled steadily: Total AUM (Mutual fund & Alternate Investment) increased by 14.7% YoY to ₹2.31 Lakh crore (Mar ’26) vs ₹2.01 lakh crore (Mar ’25) and ₹1.82 lakh crore (Mar ’24) ; supporting recurring fee income. AUM as of June 2026 is at ₹2.81 Lakh crore up by 23% YoY.
- Significant reduction in wholesale lending risk: The wholesale loan book witnessed a sharp 97% decline, falling from ₹18,000 crore (Mar 2019) to ₹600 crore by (June ‘26). This reduction of ₹17,400 crore over years has materially lowered risk levels compared to previous cycles.
- Strong liquidity and positive ALM: Expected inflows of ~₹11,900 cr along with existing liquidity of ~₹ 5700 cr comfortably cover ~₹12,300 cr of outflows over the next 1 year (July 26 to June 27) supported by positive ALM gaps across all tenors (≤1 year: +₹900 cr; 1-3 years: +₹800 cr; 3+ years: +₹4,300 cr), indicating low refinancing risk.
Weaknesses:
- Insurance businesses still drag consolidated returns: Life and general insurance arms remain loss-making, though losses have reduced versus prior years; breakeven is expected only over the next 1-2 years.
- Slow growth in retail lending: Retail and MSME lending growth has been relatively muted.
Invest Now: Invest in Bond IPO online in just 5 minutes
Source: Prospectus, September 10, 2026
Disclaimer
The information is published as of date 18/09/2026 based on information available on Prospectus September 10, 2026, Investor Presentation (Q1 FY27). The information may be subject to change in case of change in terms of prospectus or any other reason as the case may be. Contents that are exclusively for educational information/knowledge sharing on capital market concepts and have no influence on the investment/sale decisions of any investors


