
While choosing a fixed deposit investment for 2026, Federal Bank is a private sector bank that offers customers different types of deposits at various interest rates and tenures for its regular customers as well as senior citizens.
Whichever tenure of deposit you want to make, it is useful for you to know about the current interest rates and tenures offered by the bank in respect of its fixed deposits.
Disclaimer: The above information is presented only for knowledge purposes. It should not be considered advice or a recommendation to invest in any kind of financial instruments. Interest rates and deposit schemes offered by Federal Bank are subject to change.
Start investing with just ₹10K & grow your wealth with fixed return opportunities.
Invest Now
Federal Bank Fixed Deposit Interest Rates in 2026
Federal Bank offers resident term deposits with tenures ranging from 7 days to 10 years. As per the latest interest rate schedule effective from 1 November 2026, general customers can earn up to 6.80% p.a., while eligible senior citizens can earn up to 7.30% p.a. on standard callable deposits below ₹3 crore. The applicable rate depends on the deposit tenure and customer category.
| Deposit Tenure | General Customers | Senior Citizens |
|---|---|---|
| 7–29 days | 3.00% | 3.50% |
| 30–45 days | 3.25% | 3.75% |
| 46–90 days | 4.25% | 4.75% |
| 91–180 days | 4.50% | 5.00% |
| 181 days | 6.00% | 6.50% |
| 182–270 days | 5.50% | 6.00% |
| 271 days–less than 1 year | 6.00% | 6.50% |
| 1 year | 6.25% | 6.75% |
| Above 1 year–less than 15 months | 6.55% | 7.05% |
| 15 months | 6.70% | 7.20% |
| Above 15 months–24 months | 6.55% | 7.05% |
| Above 24 months–less than 48 months | 6.50% | 7.00% |
| 48 months | 6.80% | 7.30% |
| Above 48 months–10 years | 6.40% | 6.90% |
Rates are for resident term deposits below ₹3 crore. The same standard rates also apply to NRO deposits, but NRO account holders are not eligible for the senior-citizen premium. Rates are subject to change.
Features of Federal Bank Fixed Deposits
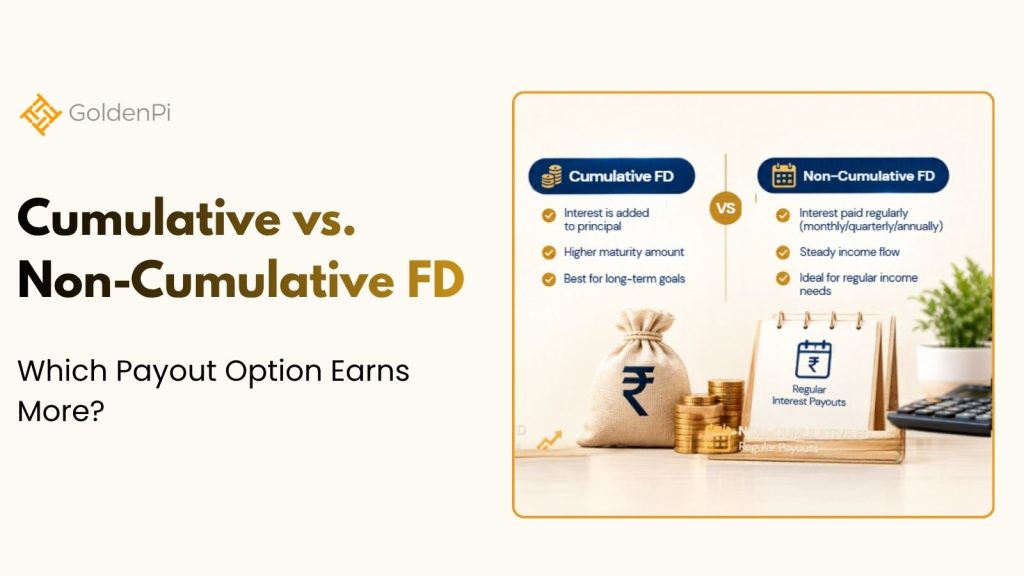
Federal Bank offers different fixed deposit options to meet customers’ financial requirements. Customers can choose cumulative deposits, such as Cash Certificates, where interest is compounded quarterly and paid along with the principal at maturity. Non-cumulative fixed deposits offer periodic interest payouts, with options such as monthly, quarterly, half-yearly or yearly payments, depending on the deposit plan.
Customers can open eligible resident fixed deposits through Federal Bank’s FedNet internet banking platform or FedMobile app, subject to the bank’s terms and conditions. FDs can also be opened at a branch. Premature withdrawal is permitted in eligible cases, but the applicable interest may be reduced by a penalty.
Special FD Rates of Federal Bank
Federal Bank offers different interest rates for specific deposit tenures, including 181 days, 15 months and 48 months. It also offers Deposit Plus, a non-callable term deposit for eligible deposits starting at ₹1 crore plus ₹1. This product does not allow premature withdrawal and has a separate interest rate schedule. Customers should compare its rate and withdrawal restrictions with those of standard callable FDs before choosing a deposit.
Latest Fixed Deposit Updates:
- FD for Minors in India: Account Rules, Taxation & Required Documents
- Cumulative vs Non-Cumulative FD: Which Payout Option Earns More?
- Callable vs Non-Callable FDs: Why Non-Callable Deposits Pay More
What about Fedfina FD?
Apart from Federal Bank, investors may also come across Fedfina (Fedbank Financial Services Limited), a separate NBFC and a subsidiary of Federal Bank. Fedfina offers financial products such as gold loans, home loans and loans against property. These are different from Federal Bank’s deposit products.
Things to Consider Before Opening a Federal Bank FD
Instead of selecting an FD solely because it offers a higher interest rate, consider whether the product suits your financial needs.
| Factor | Why It Matters |
|---|---|
| Interest Rate | Determines the return on your deposit. Compare rates across tenures and customer categories. |
| Deposit Tenure | Choose a tenure that aligns with when you may need the funds. |
| Premature Withdrawal | Federal Bank generally applies a 1% penalty on premature withdrawal of rupee term deposits below ₹3 crore if held for more than 15 days. No penalty applies if the deposit is held for 15 days or less. Premature closure may reduce the interest payable. |
| Interest Payout Option | Choose a cumulative deposit for interest at maturity or a non-cumulative deposit for periodic payouts, depending on your requirements. |
| Deposit Insurance | Eligible Federal Bank deposits are covered by DICGC insurance up to ₹5 lakh per depositor per bank, including principal and interest. Deposits across the bank’s branches are aggregated when calculating this limit, for accounts held in the same right and capacity. |
Frequently Asked Questions (FAQs)
The highest standard callable FD rate is 6.80% p.a. for general customers and 7.30% p.a. for eligible senior citizens, on a 48-month deposit.
Yes. Eligible resident fixed deposits can be opened through Federal Bank’s FedNet internet banking platform or FedMobile app, subject to the bank’s terms and conditions.
Federal Bank offers specific-tenure rates and a separate non-callable Deposit Plus product. Deposit Plus has a minimum deposit requirement of ₹1,00,00,001 and does not allow premature closure.
No. Fedfina is a separate NBFC and a subsidiary of Federal Bank. It offers lending products, whereas Federal Bank provides banking and deposit services.
Conclusion
The Federal Bank provides a variety of fixed deposits with multiple tenure options, online FD booking facilities, and additional interest for eligible senior citizens. Whether you wish to open a fixed deposit for a short period of time or are looking forward to achieving some financial goals in the long run, comparing the various tenure options, studying the related terms, and reviewing the prevailing FD rates can assist you in making an informed choice.
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


