
YES Bank’s fixed deposit rates remain competitive in 2026, with regular customers earning up to 7.25% and resident senior citizens up to 7.75% on selected tenures. But an FD decision involves more than comparing the headline rate. The bank’s financial position, deposit insurance, tenure, premature-withdrawal terms, taxation, and the alternatives available in the market all deserve consideration.
YES Bank also presents an interesting case for depositors because its financial profile has changed substantially since the bank’s reconstruction in 2020. Its latest numbers show improved profitability and asset quality, although that history remains relevant when assessing how much money to place with any one bank.
Start investing with just ₹30K & grow your wealth with fixed return opportunities.
Invest Now
YES Bank FD Interest Rates 2026
YES Bank’s published domestic FD rates for deposits below ₹3 crore, effective 2 June 2026, range from 3.25% to 7.25% for regular customers. Eligible resident senior citizens receive an additional 0.50 percentage point for tenures below three years and 0.75 percentage point for tenures of three years and above. This benefit does not apply to NRO and NRE deposits.
| FD tenure | Regular interest rate | Regular annualized yield | Senior citizen interest rate | Senior citizen annualized yield |
| 7 days to 14 days | 3.25% | 3.25% | 3.75% | 3.75% |
| 15 days to 45 days | 3.50% | 3.50% | 4.00% | 4.00% |
| 46 days to 90 days | 4.50% | 4.50% | 5.00% | 5.00% |
| 91 days to 120 days | 4.75% | 4.75% | 5.25% | 5.25% |
| 121 days to 180 days | 4.75% | 4.75% | 5.25% | 5.25% |
| 181 days to 271 days | 6.00% | 6.14% | 6.50% | 6.66% |
| 272 days to 335 days | 6.25% | 6.40% | 6.75% | 6.92% |
| 336 days to <12 months | 6.50% | 6.66% | 7.00% | 7.19% |
| 12 months | 6.65% | 6.82% | 7.15% | 7.34% |
| 12 months 1 day to <18 months | 6.75% | 6.92% | 7.25% | 7.45% |
| 18 months | 6.75% | 6.92% | 7.25% | 7.45% |
| 18 months 1 day to <24 months | 7.25% | 7.45% | 7.75% | 7.98% |
| 24 months to <35 months | 7.00% | 7.19% | 7.50% | 7.71% |
| 35 months | 6.90% | 7.08% | 7.40% | 7.61% |
| 35 months 1 day to <36 months | 7.00% | 7.19% | 7.50% | 7.71% |
| 36 months to <60 months | 7.00% | 7.19% | 7.75% | 7.98% |
| 60 months | 6.75% | 6.92% | 7.50% | 7.71% |
| 60 months, 1 day to ≤120 months | 6.75% | 6.92% | 7.50% | 7.71% |
Source: Yes Bank
The highest published rate for regular customers is therefore 7.25%, available on deposits from 18 months and 1 day to less than 24 months. For senior citizens, the highest interest rate is 7.75%, available on deposits from 18 months and 1 day to less than 24 months and from 36 months to less than 60 months.
How Much of a YES Bank FD Is Insured?
DICGC deposit insurance is an important consideration when evaluating any bank FD. Eligible deposits, including fixed deposits, are insured for up to ₹5 lakh per depositor per bank, including principal and interest. Deposits held across different branches of the same bank are aggregated when determining the insurance limit. This means an investor with ₹20 lakh available for fixed deposits should not assume that the entire amount is covered merely because it is placed in an insured bank.
For larger FD portfolios, spreading deposits across different banks can increase the amount covered under separate DICGC limits, subject to the applicable rules. YES Bank appears on DICGC’s current list of insured banks, which was updated on October 19, 2026.
YES Bank FD vs. Other Bank FDs: What Should You Compare?
The most useful comparison isn’t simply which bank offers the highest rate. Investors can compare the interest rate with the tenure, deposit-insurance coverage, liquidity requirements, and the bank’s financial position.
For example, a difference of 0.75 percentage point on a ₹10 lakh deposit represents ₹7,500 of additional simple annual interest before tax. Whether that difference matters will depend on the investor’s circumstances and the other terms attached to the deposits being compared.
This is particularly relevant when comparing YES Bank with larger private- or public-sector banks. A higher advertised rate can be attractive, but the decision should also account for concentration risk and whether the chosen tenure matches the investor’s cash-flow requirements.
FD Alternatives to YES Bank in 2026
Investors comparing fixed deposits have several categories to consider rather than looking for a single “best” option. Small finance banks, for instance, can offer higher FD rates than many larger banks on selected tenures. The additional interest, however, needs to be considered alongside the financial profile of the issuing bank and the investor’s approach to diversification.
Government-backed fixed-income instruments can provide a different risk profile altogether. Treasury Bills and Government securities are available through RBI’s Retail Direct framework, while listed bonds provide another route to fixed-income exposure. Unlike an FD held to maturity, however, bonds can fluctuate in market value before maturity.
The comparison therefore comes down to more than the headline yield: what is the risk being taken, when is the money needed, and how easily can the investment be exited?
Latest Fixed Deposit Updates:
- FD for Minors in India: Account Rules, Taxation & Required Documents
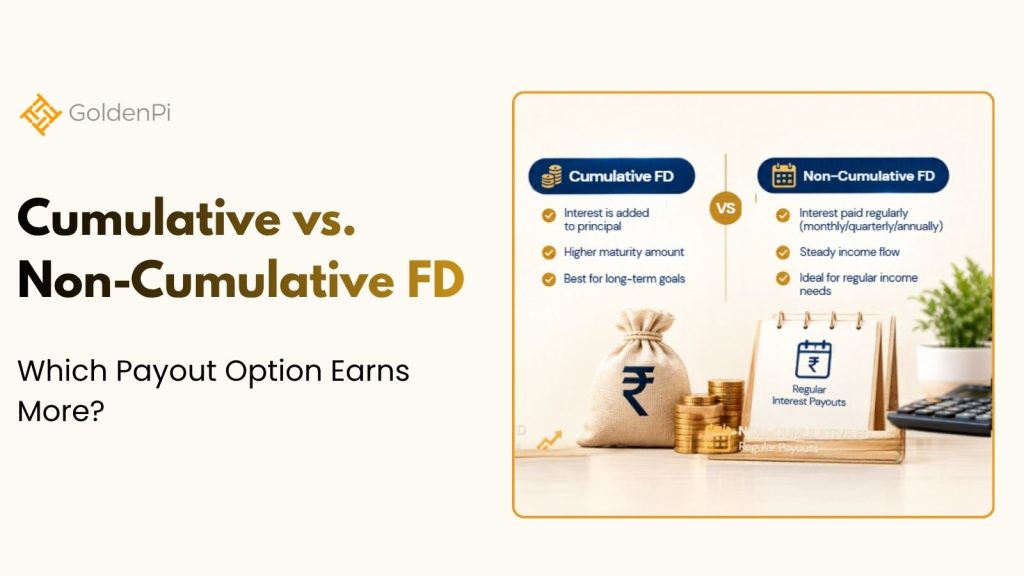
- Cumulative vs Non-Cumulative FD: Which Payout Option Earns More?
- Callable vs Non-Callable FDs: Why Non-Callable Deposits Pay More
YES Bank FD Premature Withdrawal and Liquidity
YES Bank permits premature withdrawal of eligible FDs, although the interest payable may be lower than the contracted rate and a penalty may apply.
For deposits below ₹5 crore, the published penalty is 0.75% for deposits held for up to 181 completed days and 1% for deposits held for 182 days or more. However, senior-citizen FDs booked or renewed on or after 16 May 2022 are exempt from this penalty. The penalty also applies to partial withdrawals and withdrawals through the sweep-in facility.
No interest is paid if a resident or NRO FD is closed within seven days of booking. For NRE deposits, no interest is paid if the deposit is closed before completing one year. Investors who may need access to their money before maturity should therefore compare premature-withdrawal terms rather than selecting an FD solely on its advertised rate.
Tax on YES Bank FD Interest
Interest earned on a YES Bank FD is taxable according to the applicable income-tax rules and the investor’s tax position. Under Section 393 of the Income Tax Act, 2025, TDS on bank deposit interest generally applies when the aggregate interest exceeds ₹50,000 for non-senior citizens or ₹1 lakh for senior citizens. The applicable TDS rate and other conditions should also be considered.
As a result, the post-tax return can be more useful for comparison than the advertised FD rate. An investor should also consider whether the interest is being received periodically or accumulated until maturity when planning cash flows.
Is YES Bank FD Safe in 2026?
A meaningful safety assessment needs to look at the bank’s current financial position as well as its history.
In March 2020, the RBI placed YES Bank under a moratorium and subsequently implemented a reconstruction scheme after the bank faced serious financial and liquidity challenges. The bank’s financial performance and asset quality have since improved. In Q2 FY27, ended September 2026, YES Bank reported standalone net profit of ₹1,080 crore, up 65% year-on-year. Deposits increased 19.5% year-on-year to ₹3.54 lakh crore, while the gross NPA ratio stood at 1.2% and the net NPA ratio at 0.2%. Its CET-1 ratio was 13.7%.
However, these reported results do not reflect the potential financial impact of the Supreme Court’s 15 October 2026 judgment concerning the bank’s ₹8,415 crore AT1 bond write-down. In an indicative, unaudited pro forma scenario, YES Bank estimated that recognising the impact could have resulted in a net loss of ₹5,217 crore for Q2 FY27 and a CET-1 ratio of 11.4%, compared with the reported 13.7%. The bank is assessing the implications and the appropriate accounting and regulatory treatment.
These developments are important context when assessing the bank’s financial position. They do not establish that depositors will incur losses, but they reinforce the importance of considering bank-specific risk, DICGC coverage, and diversification when deciding how much to deposit with one bank.
Who May Consider a YES Bank FD in 2026?
YES Bank FDs can be included in comparisons of bank deposits, including for investors looking at the 18–24 month range where the bank currently offers its highest regular-customer rate.
The appropriate choice will depend on the investor’s investment horizon, liquidity needs, tax position, and overall diversification. For a sizeable FD allocation, concentrating the entire amount in one bank may expose the investor to unnecessary bank-specific concentration, regardless of the interest rate offered.
The broader lesson is that FD selection is a trade-off between interest income, liquidity, diversification, and the financial profile of the bank.
YES Bank Fixed Deposits Frequently Asked Questions
Yes, YES Bank generally offers an additional interest rate to eligible senior citizens on applicable deposits. The exact benefit depends on the tenure and prevailing rate card.
Yes. Interest earned on a YES Bank FD is generally taxable at the applicable rate. TDS may also apply when the interest crosses the prescribed threshold, subject to the applicable rules.
Premature withdrawal is generally permitted, subject to the applicable penalty. For deposits below ₹5 crore, the penalty is 0.75% up to 181 completed days and 1% from 182 days onward. Eligible senior-citizen deposits booked or renewed from 16 May 2022 are exempt from this penalty. No interest is paid on resident and NRO deposits closed within seven days.
Depending on your objectives, alternatives can include other bank FDs, Post Office schemes, government securities, high-quality corporate bonds, and debt mutual funds. Each has different levels of risk, liquidity, and taxation.
Check the latest interest rate, tenure, senior-citizen benefit if applicable, premature-withdrawal rules, TDS implications, nomination details, and DICGC coverage. For larger deposits, consider whether concentrating the entire amount in one bank is appropriate.
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


