
A 5-Year Fixed Deposit (FD) can be considered by investors who want to lock in a fixed interest rate for a longer period. Whether it is for planned future expenses or a preference for fixed returns, a 5-year FD allows you to keep money in a bank deposit for a defined period.
However, not all banks offer the same interest rate on a 5-year FD. Rates vary depending on the bank, customer segment, deposit amount and prevailing interest-rate environment. Before opening an FD, consider factors such as interest rates, liquidity, premature withdrawal terms, deposit insurance and taxation.
Disclaimer: The information presented here is meant for educational purposes only and should not be considered investment advice or a recommendation to invest in any financial product. The interest rates can change from time to time, as per different banks.
5-Year Fixed Deposit Interest Rates in November 2026
Based on rate comparisons available up to 28 October 2026, public-sector banks offered approximately 5.00%–6.30% p.a., while private-sector banks offered approximately 5.70%–6.75% p.a. on five-year deposits. Some Small Finance Banks offer higher rates, with Suryoday listing 8.25% p.a. on its five-year tax-saver FD.
| Bank Category | Indicative 5-Year FD Interest Rate |
|---|---|
| Public Sector Banks | Approximately 5.00%–6.30% p.a. |
| Private Sector Banks | Approximately 5.70%–6.75% p.a. |
| Small Finance Banks | Up to 8.25% p.a. |
| Senior Citizens | Additional interest varies by bank and tenure; Suryoday lists 8.50% p.a. on its five-year tax-saver FD |
Note: Rates are indicative and may vary by deposit amount, product type and customer category. The public- and private-sector ranges are based on a comparison dated 28 October 2026.
Start investing with just ₹30K & grow your wealth with fixed return opportunities.
Invest Now
Why Do Investors Choose a 5-Year Fixed Deposit?
It is common for investors who want assured returns without needing funds until the end of the FD tenure to go for a 5-year FD. Returns are not dependent on any change in the interest rates since the rate of interest is fixed while booking the FD.
Some investors also consider a five-year tenure because eligible tax-saving bank deposits can qualify for a deduction under Section 123 read with Schedule XV of the Income-tax Act, 2025. The deduction is subject to an overall limit of ₹1.5 lakh across specified eligible investments and payments. It is available only under the applicable tax regime and is not permitted under the new concessional tax regime. Ordinary five-year bank FDs do not automatically qualify.
Points That You Should Keep in Mind While Opening a 5-Year FD
While the interest rate is indeed important, it is not the only point to consider.
Other points to take into account before investing are:
- Interest rate offered for the desired tenure.
- Penalty for premature closure.
- Interest payment options (monthly/quarterly/cumulative).
- Taxability of interest earned.
- Whether the bank is covered by DICGC and how much of your total deposits are insured.
- Does a five-year commitment of your money meet your financial objectives?
DICGC insurance covers eligible deposits up to ₹5 lakh per depositor per bank, including principal and interest. Deposits across branches of the same bank are aggregated, subject to the same-right-and-same-capacity rules.
Latest Fixed Deposit News:
- FD for Minors in India: Account Rules, Taxation & Required Documents
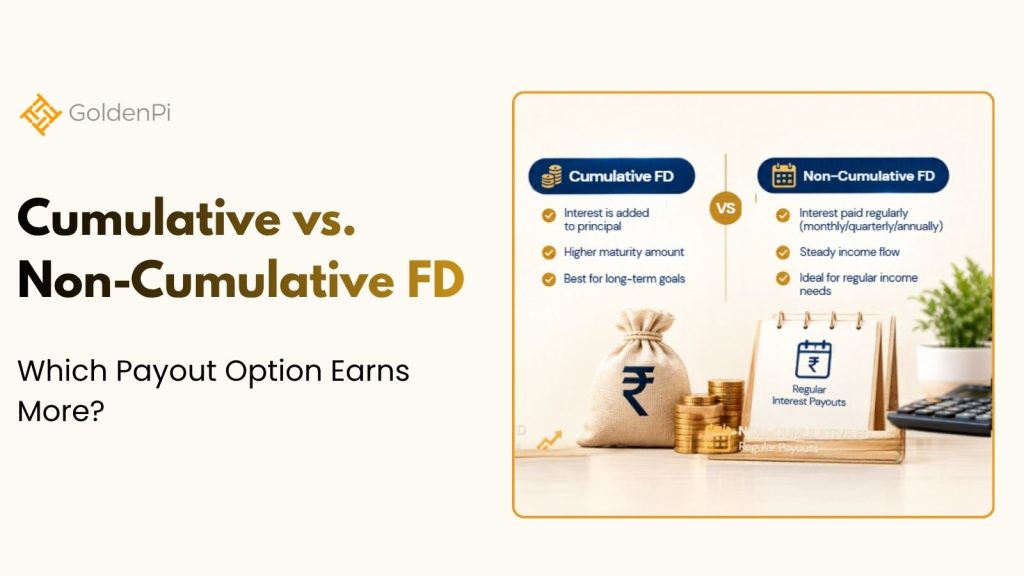
- Cumulative vs Non-Cumulative FD: Which Payout Option Earns More?
- Callable vs Non-Callable FDs: Why Non-Callable Deposits Pay More
5-Year Fixed Deposits and Other Fixed-Income Investments
A five-year fixed deposit is one option for investors seeking predictable returns, but it is worth comparing it with other fixed-income products before investing. Post Office Time Deposits (POTD), National Savings Certificates (NSC) and Senior Citizens’ Savings Scheme (SCSS) offer government-backed alternatives, with rates and eligibility conditions that differ.
For October–December 2026, the interest rates are 7.50% for a five-year POTD, 7.70% for NSC and 8.20% for SCSS. SCSS is primarily available to eligible senior citizens, while POTD and NSC are open to a broader investor base.
| Investment | Interest rate | Tenure | Key consideration |
|---|---|---|---|
| 5-year Bank FD | Varies by bank | 5 years | Returns depend on the bank and applicable rate card; eligible tax-saver FDs may qualify for a tax deduction |
| Post Office 5-year TD | 7.50% | 5 years | Government-backed; eligible for tax deduction under Section 123, subject to applicable conditions |
| National Savings Certificate (NSC) | 7.70% | 5 years | Government-backed; interest is generally reinvested, with tax treatment subject to applicable rules |
| Senior Citizens’ Savings Scheme (SCSS) | 8.20% | 5 years | Available to eligible investors; interest is paid quarterly |
Bank FDs and Post Office TDs offer a relatively predictable return over the deposit term, while NSC accumulates interest until maturity. SCSS offers quarterly interest payouts, making it relevant for eligible investors seeking regular income.
Before choosing, compare the effective return after tax, premature withdrawal rules and eligibility requirements. Also remember that bank deposits are covered by DICGC insurance only up to ₹5 lakh per depositor per bank, including principal and interest.
Frequently Asked Questions (FAQs)
Some Small Finance Banks offer higher five-year FD rates than larger banks. Suryoday Small Finance Bank currently lists 8.25% p.a. for regular customers and 8.50% p.a. for senior citizens on its five-year tax-saver FD. Investors should check the bank’s latest rate card before booking.
Only eligible five-year tax-saving bank deposits qualify for a deduction under Section 123 read with Schedule XV of the Income-tax Act, 2025. The deduction forms part of the overall ₹1.5 lakh limit and is not available under the new concessional tax regime. Ordinary five-year FDs do not automatically qualify.
Many banks permit premature withdrawal of regular FDs, although it may be subject to a penalty or reduced interest and the bank’s applicable terms. Tax-saving FDs generally have a five-year lock-in and do not permit premature withdrawal except in specified circumstances.
No. Fixed deposits are bank deposit products, whereas bonds are debt securities issued by governments or companies. They have different features, risks, liquidity, and return structures.
Closing Thoughts
A 5-year fixed deposit can suit investors who want to lock in a fixed interest rate for a defined period. However, the interest rate is only one factor to consider. Premature withdrawal rules, liquidity, taxation, deposit insurance and whether the five-year tenure matches your financial needs are also important. Comparing these features across different fixed-income products can help investors understand how each option works before making a decision.
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


