
Have you ever filled out a fixed deposit form at a post office counter and wondered why the rate on the form doesn’t match what your account earns each year? That gap isn’t a calculation error; it is simply compounding at work. Post Office Fixed Deposits, also known as National Savings Time Deposits, are still a popular choice for conservative Indian savers in 2026 because they are backed by the government and have certain, predetermined tenures.
They also offer competitive rates, with the one-year deposit earning 6.9% and the five-year deposit earning 7.5%. This article walks you through the latest rate chart, how quarterly compounding quietly works in your favor even though you’re paid once a year, and how this scheme compares with a regular bank FD.
Start investing with just ₹30K & grow your wealth with fixed return opportunities.
Invest Now
Latest Post Office FD Interest Rates 2026 (Tenure-Wise)
Small Savings Scheme rates are reviewed by the Ministry of Finance every quarter. The current Post Office Time Deposit rates are 6.90% for one year, 7.00% for two years, 7.10% for three years and 7.50% for five years. These rates have remained unchanged since January 2024. The rates applicable when you open the account continue for the full deposit tenure, even if the government revises rates for new deposits in a later quarter. The current tenure-wise rates for the October-December 2026 quarter are:
| Tenure | Interest Rate (p.a.) | Annual interest rate after quarterly calculation | Section 123 Deduction |
| 1 year | 6.90% | ~7.08% | No |
| 2 years | 7.00% | ~7.19% | No |
| 3 years | 7.10% | ~7.29% | No |
| 5 years | 7.50% | ~7.71% | Yes |
Source: India Post
Note: Only the five-year Time Deposit qualifies for the deduction, subject to the conditions and overall limit under Section 123 read with Schedule XV of the Income Tax Act, 2025. The deduction is not available under the new tax regime.
How Quarterly Compounding Actually Works
This is the part that confuses most people: Post Office FD interest is compounded quarterly but paid out annually. This means your money grows every quarter but only gets credited once a year.
The maturity value is calculated as
A = P × (1 + r/4)^(4t)
where P is your deposit, r is the annual rate as a decimal, and t is the tenure in years. The rate is divided by four because it compounds every quarter, and the exponent tracks how many quarters your money sits invested.
For example, consider a ₹1,00,000 deposit in a five-year Post Office Time Deposit at 7.50% p.a. Interest is calculated quarterly, so the interest for each year works out to approximately ₹7,714. This amount is paid annually, while the original deposit remains invested. The same annual interest calculation applies during the five-year term; interest already paid or due is not automatically reinvested to earn further interest under the scheme.
Why Annual Payouts Still Matter
Even though compounding happens quarterly, the interest itself is calculated quarterly and credited to your account annually. In practical terms:
- Interest is calculated with quarterly compounding within each year. The resulting amount is payable annually, rather than being automatically reinvested for the following year.
- You still only receive a lump sum credit once a year, not every three months, so this isn’t a monthly-income product.
- If you need regular income instead of annual payouts, the Post Office Monthly Income Scheme (POMIS) is a better fit, though it currently runs at a different rate structure.
- The rate that you get at the time of your deposit is guaranteed to be the rate for the entire tenure, even if interest rates change subsequently.
Latest Fixed Deposit Updates:
- FD for Minors in India: Account Rules, Taxation & Required Documents
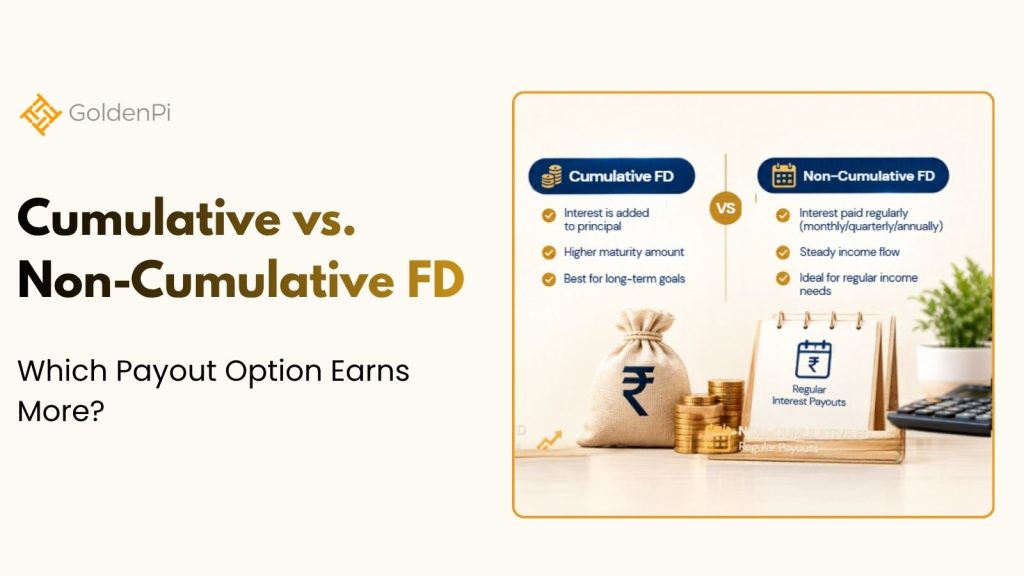
- Cumulative vs Non-Cumulative FD: Which Payout Option Earns More?
- Callable vs Non-Callable FDs: Why Non-Callable Deposits Pay More
Is It Still Worth It in 2026?
Post Office FDs may not offer the highest rates available, as some small finance banks and corporate FDs pay more. What they offer instead is certainty: government backing, no separate higher interest rate for senior citizens, and a fixed rate that remains unchanged throughout the deposit tenure.
This makes them suitable for conservative investments, such as a child’s education corpus or balancing an equity-heavy portfolio. However, they may be less suitable for emergency funds, since premature closure is restricted during the first six months and is subject to specific conditions thereafter. Interest earned is fully taxable according to the investor’s applicable income-tax slab.
One practical tip: rather than putting all your money into a single five-year deposit, consider laddering your deposits across different tenures (1, 2, 3 and 5 years). This staggers maturity dates, so a portion of your money becomes available at different intervals instead of having everything locked in for five years.
Bottom line: Post Office FDs remain a government-backed option for conservative investors in 2026. Pair the headline rate with some planning around tenure, liquidity and tax.
Post Office FD Frequently Asked Questions
Post Office Time Deposits are available for 1, 2, 3, and 5 years. The applicable interest rate depends on the tenure selected.
The interest is calculated and compounded quarterly, although it is paid to the account holder annually.
It means Interest is calculated quarterly and paid annually. The amount due at the end of each year is not automatically reinvested to earn further interest. The quarterly calculation does not mean that investors receive four separate payouts every year.
No. The standard Post Office Time Deposit structure provides for annual interest payment, not a monthly payout option. Investors looking specifically for monthly income may need to consider a different Post Office scheme.
The minimum deposit is generally ₹1,000, with deposits accepted in multiples of ₹100 thereafter. Investors should verify the latest operational rules before opening an account.
There is generally no maximum deposit limit for a Post Office Time Deposit, although the applicable scheme rules should be checked before investing a large amount.
Disclaimer
Fixed returns do not constitute guaranteed or assured returns. Investments in corporate debt securities and municipal debt securities/securitized debt instruments are subject to credit risks, market risks, and default risks, including delay and/or default in payment. Read all the offer-related documents carefully. This blog/article should not be construed as financial advice or as an offer or recommendation to buy or sell any security or any products/services of/on GoldenPi or any product/services of its third-party client(s). For a detailed calculation of YTM, visit our website. T&C’s Apply.


